LDI/Defined Benefit Highlights
- The funded ratio of the Milliman 100 Pension Funding Index increased by 5.09% in the Q3 2026, reaching 114.5%, its highest level since 2001.
- Improved funded ratios for the quarter were supported by higher yields and strong equity performance, as the S&P 500 reached another all-time high.
- AI-driven debt issuance and wider AA-rated hyperscaler spreads have lifted corporate pension discount curves, reducing liabilities and strengthening funded status, all else equal, but increasing concentration and potential downgrade risk.
- With US corporate pension plans now well funded, industry advocates are seeking reforms that would let sponsors use surplus DB assets to fund 401(k)s or health-and-welfare plans without terminating their pension plans.
- US PRT buyout and buy-in sales totaled ~$3 billion in Q2 2026, down 26% year over year, as the absence of large transactions weighed on premium volume. However, contract volume rose 21% to 176 contracts, reflecting continued activity among small and midsized plan sponsors.
- Following an uptick in PRT litigation in recent years, no new PRT lawsuits have been publicly reported in 2026 to date, suggesting a potential slowdown in filings.
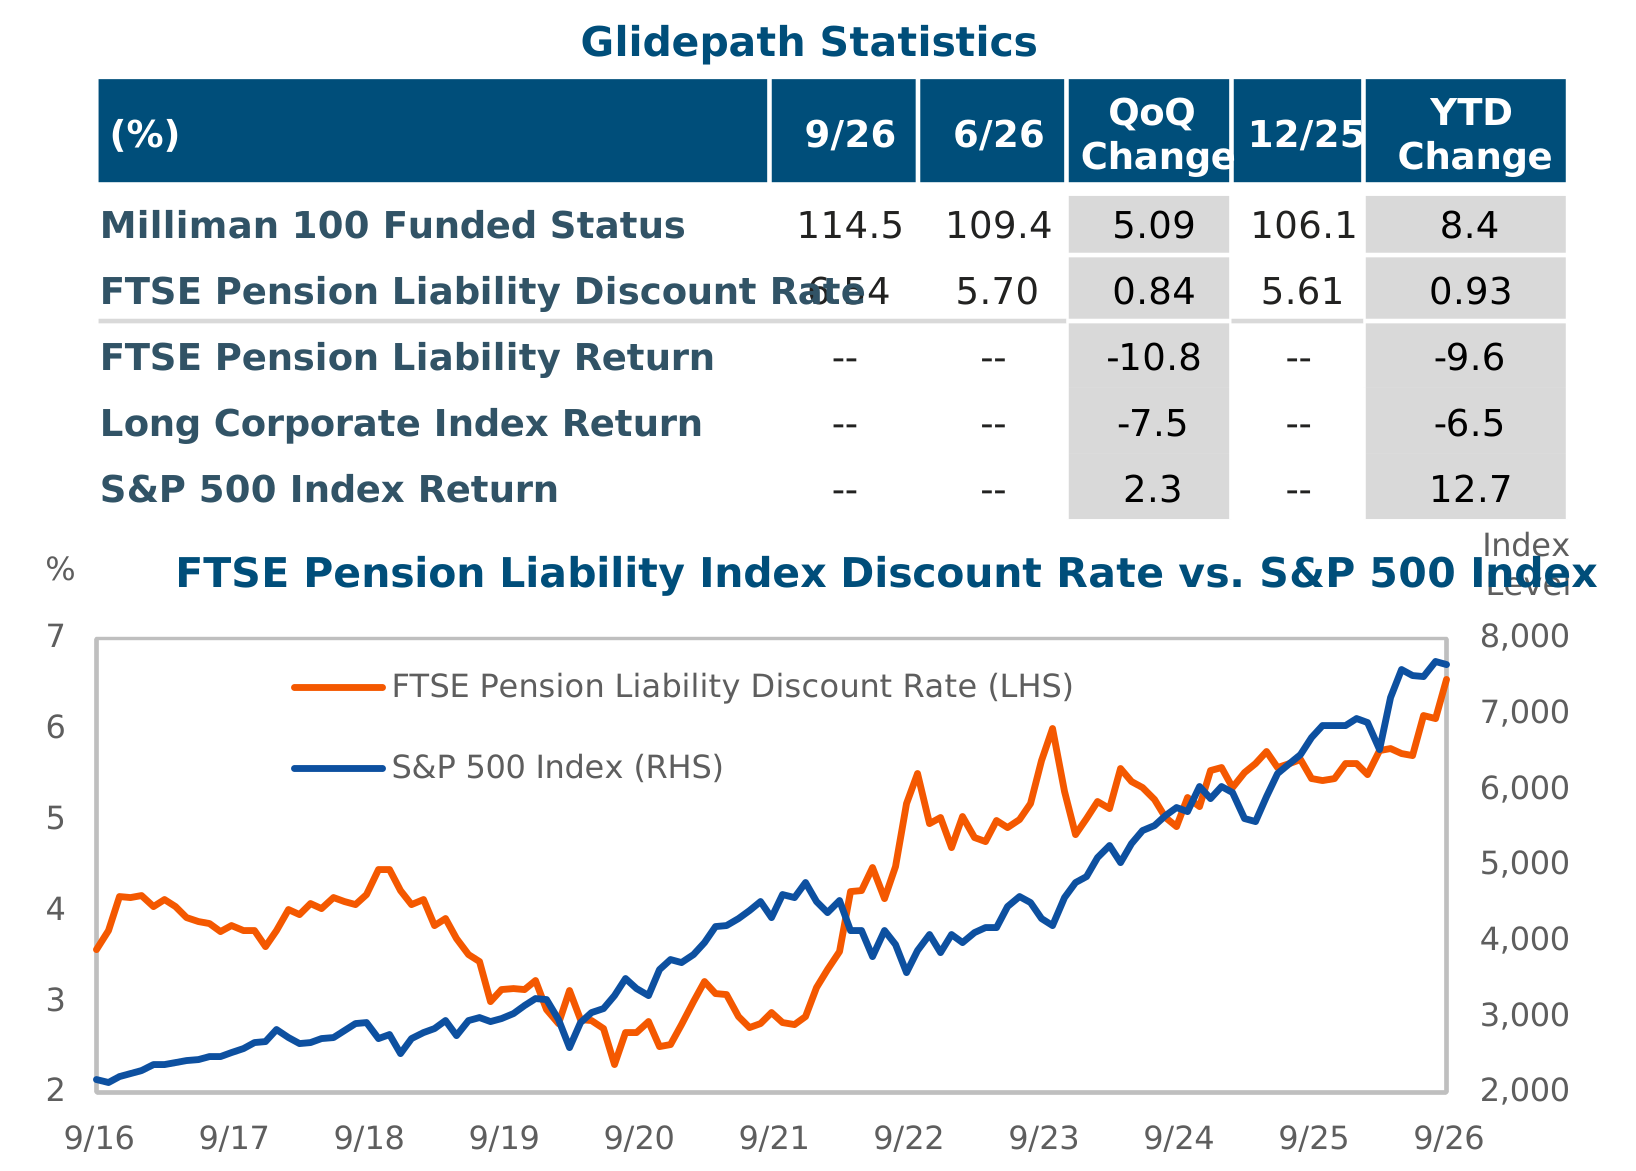
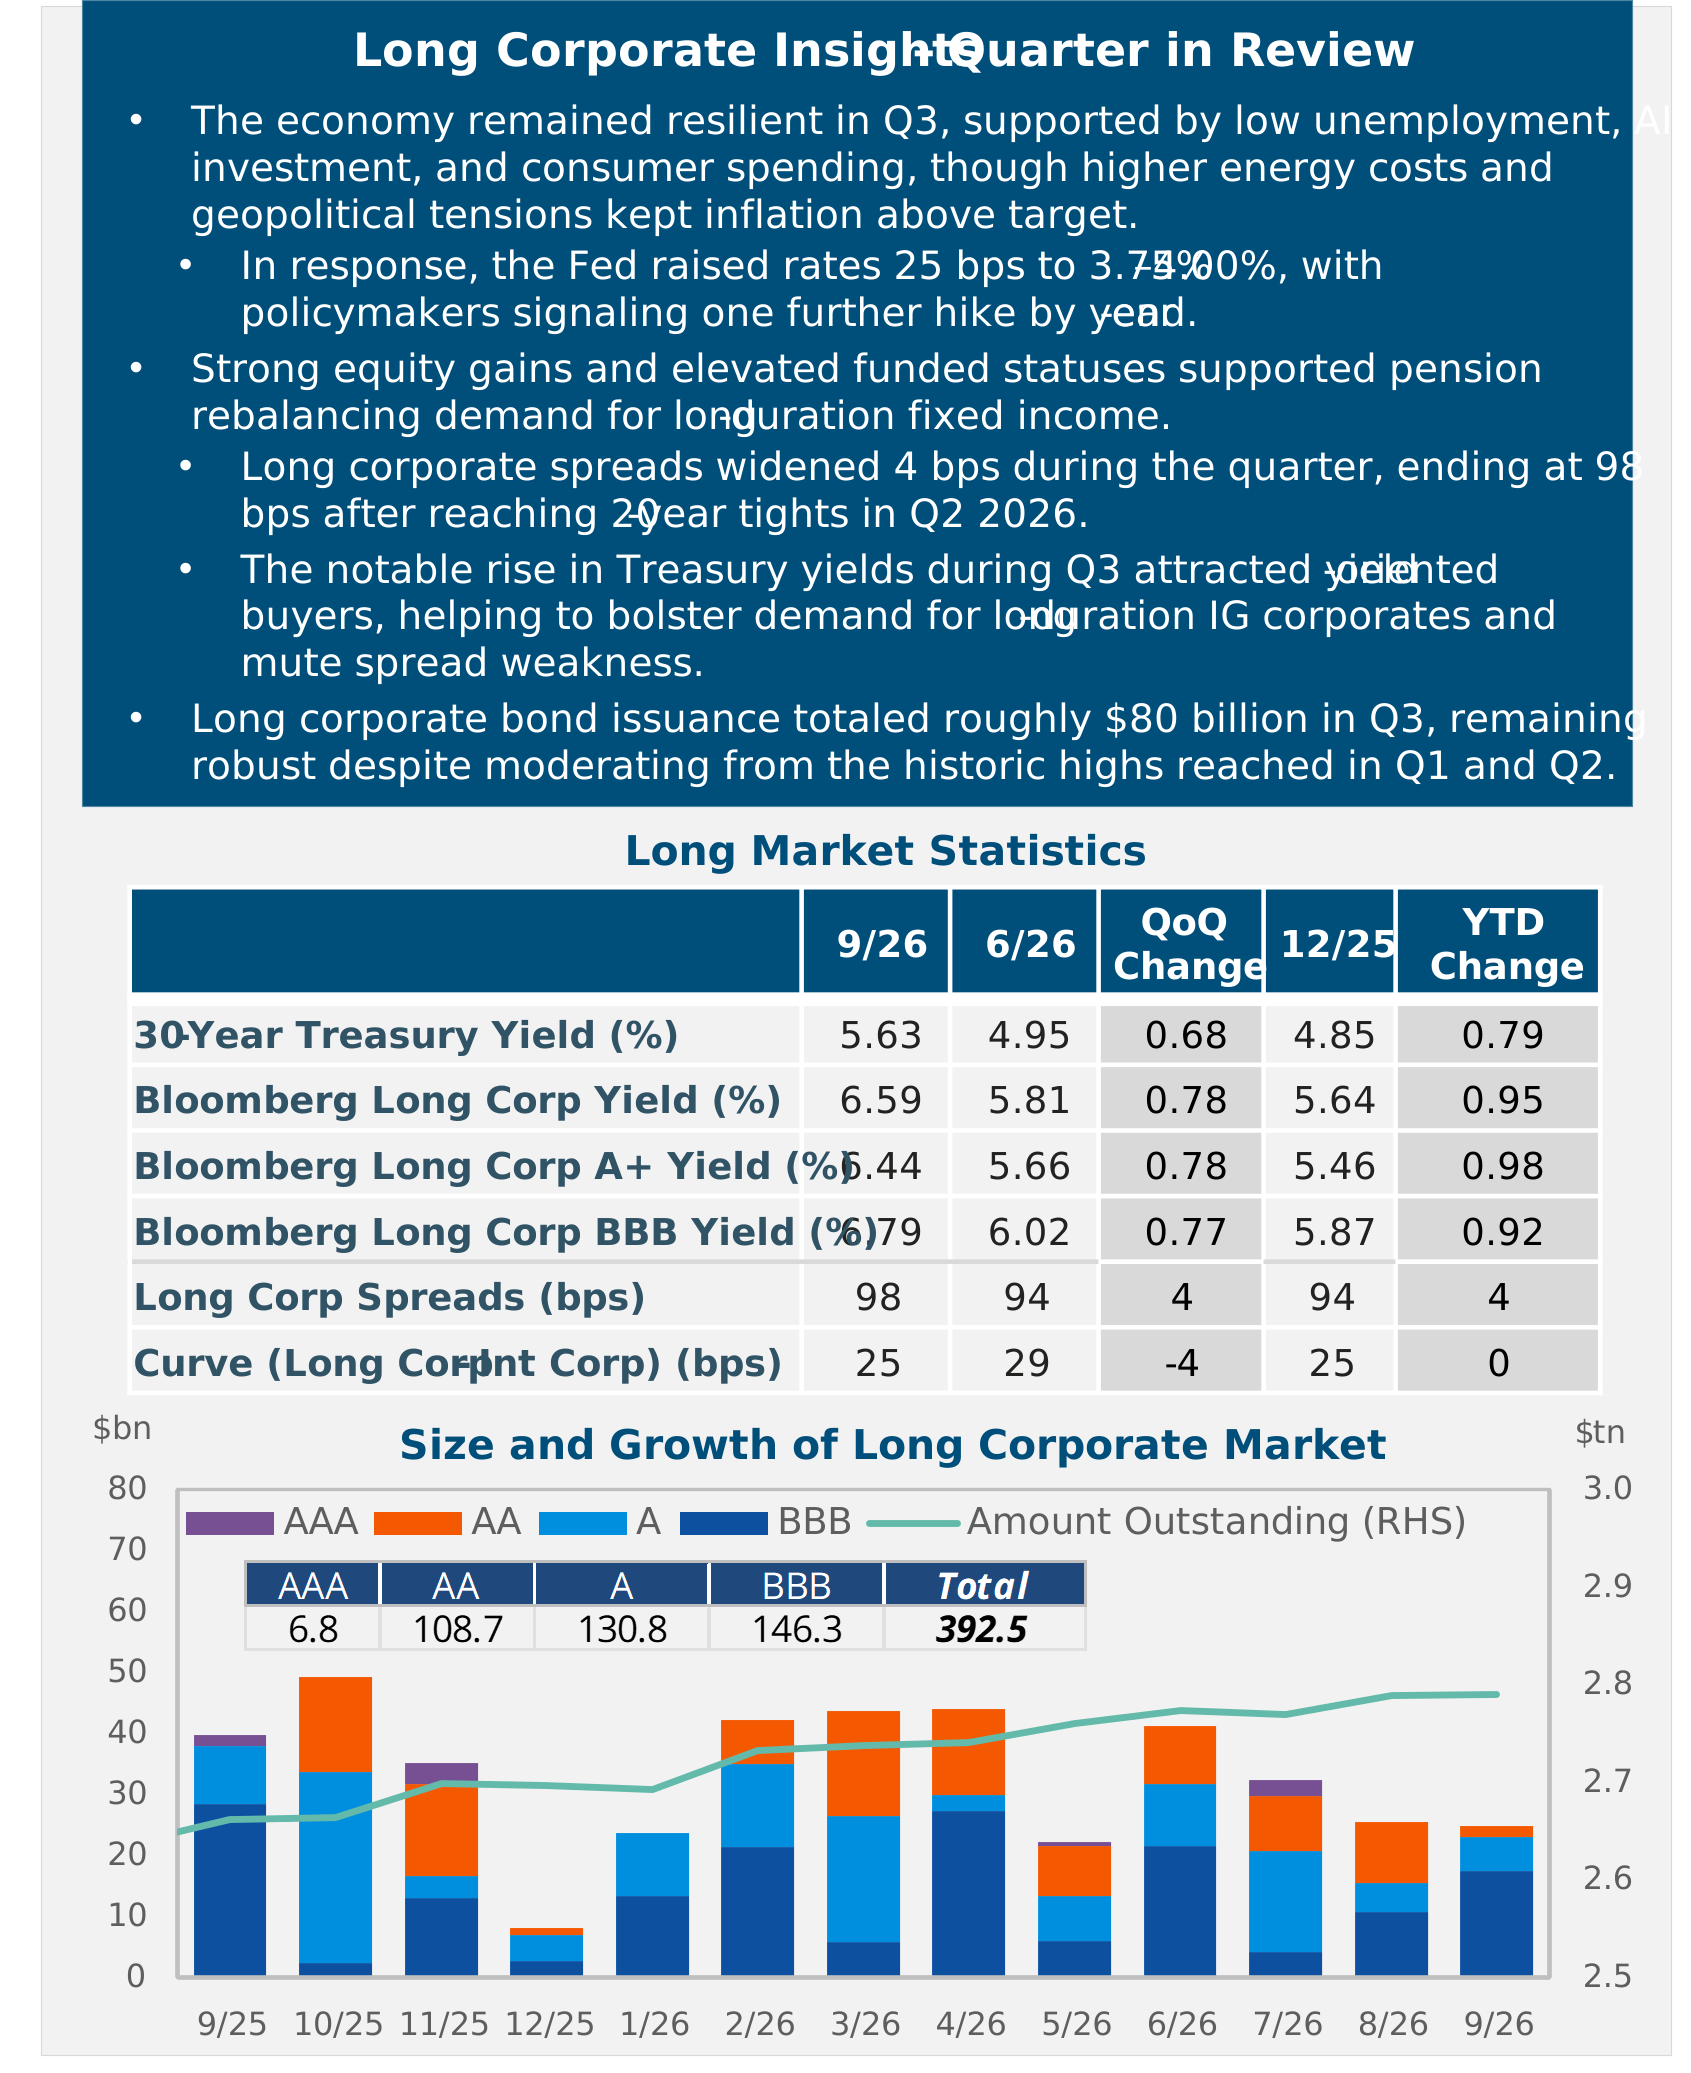
Source: Bloomberg, LIMRA, FTSE Russell (formerly Citigroup), Pensions & Investments (Surplus flexibility, PBGC premium reform top corporate pension needs 20 years after Pension Protection Act; 9/2/26), and Encore Fiduciary (Pension Risk Transfer Litigation: No New Cases but New Developments in Existing Cases Show This Litigation Trend is Not Over; 9/15/2026). Unless otherwise stated, all data in the above commentary is as of 9/30/2026. Long Corporate Index is the Bloomberg Long Corporate Index. Long issuance figures exclude 10-year bonds. The table in the long issuance chart shows the 12-month running total investment grade issuance by rating in USD billions. Totals may not sum due to rounding.
Sources: FTSE Russell (formerly Citigroup), and Bloomberg. All data in the above commentary is as of 9/30/26. Yields are represented as of the aforementioned date and are subject to change. The views contained in this report are those of Income Research + Management (“IR+M”) and are based on information obtained by IR+M from sources that are believed to be reliable but IR+M makes no guarantee as to the accuracy or completeness of the underlying third-party data used to form IR+M’s views and opinions. This report is for informational purposes only and is not intended to provide specific advice, recommendations, or projected returns for any particular IR+M product. Investing in securities involves risk of loss that clients should be prepared to bear. More specifically, investing in the bond market is subject to certain risks including but not limited to market, interest rate, credit, call or prepayment, extension, issuer, and inflation risk. “Bloomberg®” and Bloomberg Indices are service marks of Bloomberg Finance L.P. and its affiliates, including Bloomberg Index Services Limited (“BISL”), the administrator of the index (collectively, “Bloomberg”) and have been licensed for use for certain purposes by IR+M. Bloomberg is not affiliated with IR+M, and Bloomberg does not approve, endorse, review, or recommend the products described herein. Bloomberg does not guarantee the timeliness, accurateness, or completeness of any data or information relating to any IR+M product. This material may not be reproduced in any form or referred to in any other publication without express written permission from IR+M.