While markets mostly embraced the midterm results, not every sector rejoiced. Select data center bonds came under pressure as the midterm elections gave public opposition the chance to turn concerns into tighter state and local regulation. The AI buildout itself will likely remain largely intact, but the path to financing it may be bumpier, particularly in high yield, where construction, tenant, and refinancing risks are magnified. The moves were far from uniform, as projects with existing permits or already under construction are looking more valuable and scarce. Five years into managing our standalone High Yield strategy, we have learned that across cycles, broad themes rarely tell the whole story. We believe the opportunity lies in the differences underneath, not in the headline.

- Investors enjoyed a more constructive market tone following the midterm elections, as Democrats gained control of both chambers of Congress, raising questions about the outlook for fiscal policy, the Iran conflict, and AI-related infrastructure investment
- Despite gaining control of Congress, Democrats face limits on major legislative changes given President Trump's veto power, potentially increasing the likelihood of policy gridlock
- September JOLTS report was stronger than expected, offering a counterpoint to recent signs of weakening labor market demand; job openings rose by 333k last month to 7.52 million, above estimates of 7.16 million
- Investors awaited Friday’s nonfarm payrolls report for further clarity on labor market conditions and whether stronger job openings can translate to improved hiring
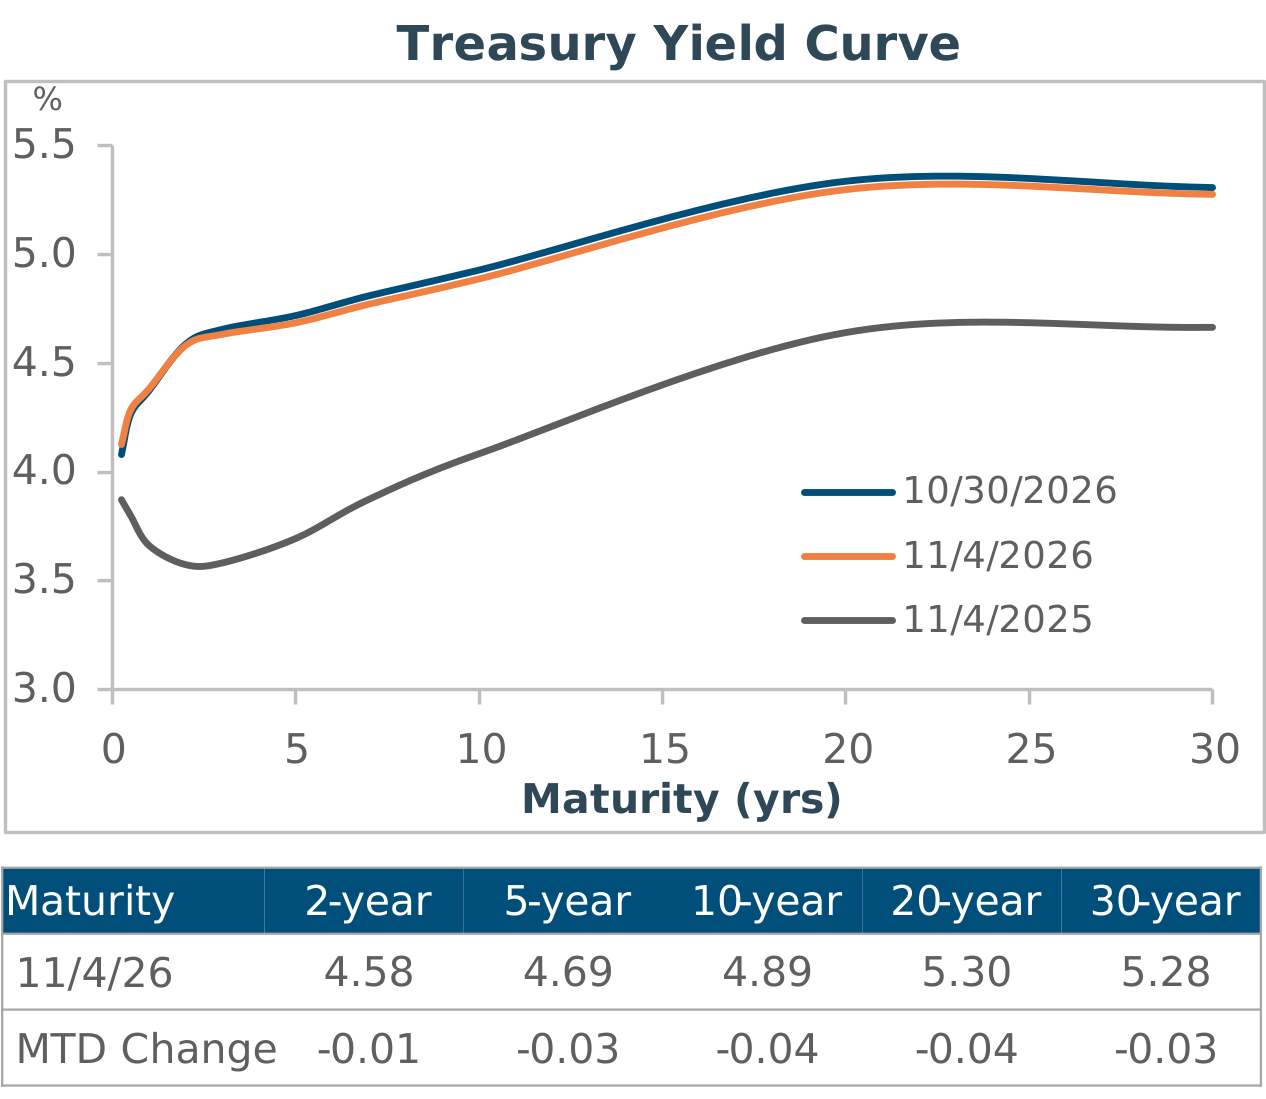
- Treasury yields were modestly lower month-to-date as investors assessed the potential fiscal implications of a divided government and updated Treasury issuance guidance, which suggested greater flexibility around future auction sizes
- The 10-year Treasury yield reached as high as 4.97% before settling at 4.89%, the lowest level since September
- Investment-grade corporate issuance totaled $74 billion this week, making it one of only eight weeks in which supply surpassed $60 billion; meanwhile, long supply has been limited as issuers remained reluctant to lock in elevated borrowing costs
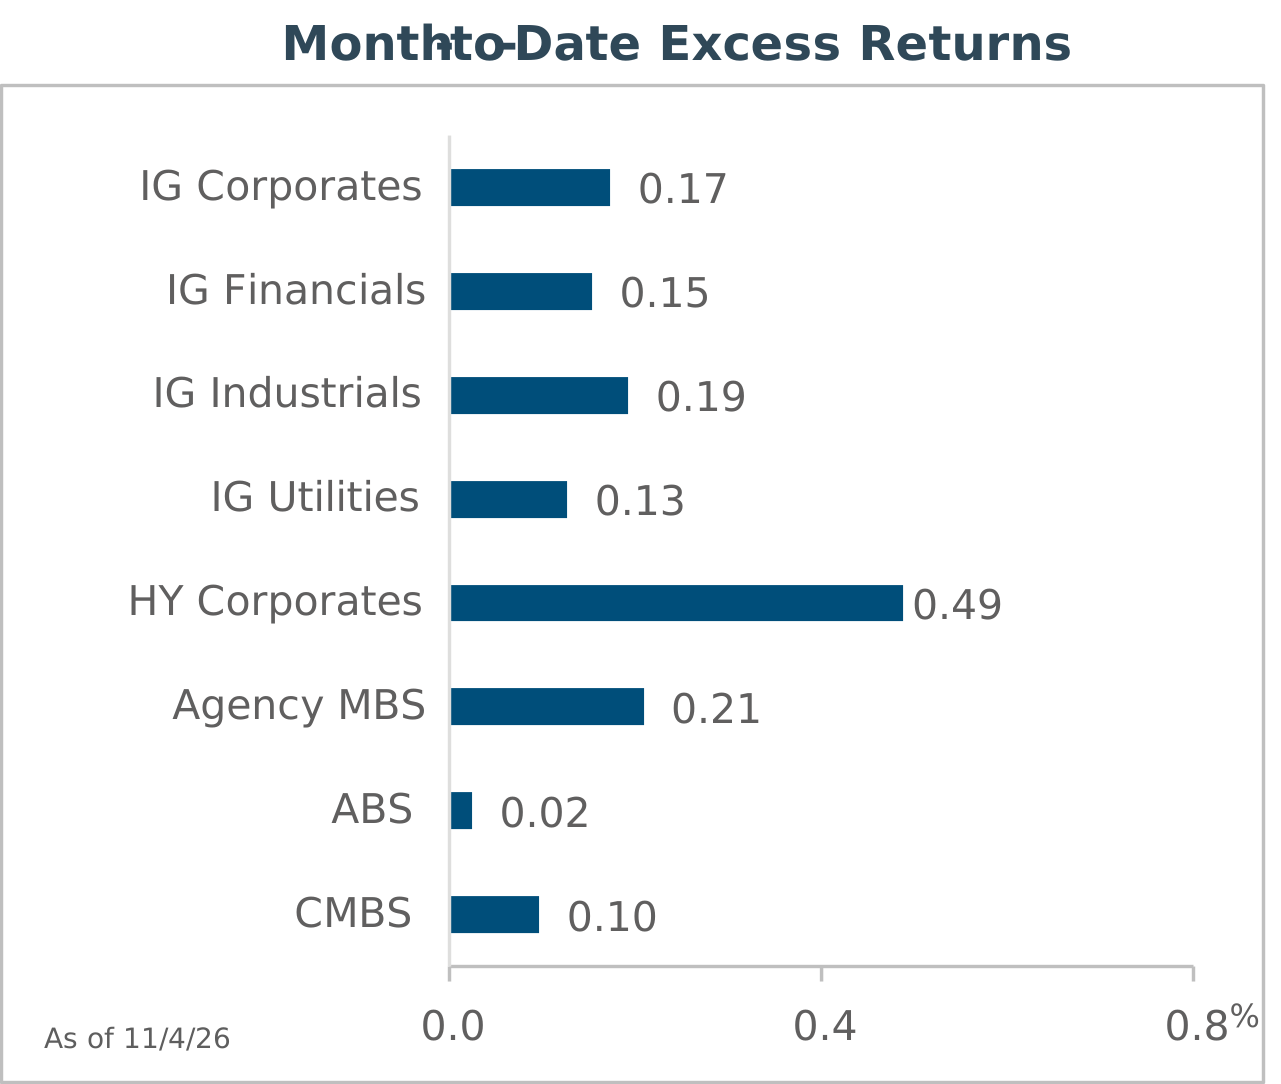
- Despite heavy issuance, investment-grade corporate spreads tightened 1bp month-to-date to 89bps
- High-yield corporate spreads tightened 16bps to 324bps amid improved risk sentiment; the firmer backdrop attracted borrowers, with over $9 billion pricing month-to-date
- Asset-backed securities (ABS) outperformed Treasuries, but could not keep pace with the the broader investment-grade market; the sector’s higher-quality nature and shorter-duration profile caused the sector to lag amid the risk-on tone
- Municipals outperformed Treasuries with muni/Treasury ratios across the curve falling by roughly 1-2%