Monthly Fixed Income Market Update: September 2026

2 min read
Share this post
Printable Version


MARKET NEWS


  • In September, the Federal Reserve (Fed) raised the federal funds target range 25bps to 3.75%-4.00%, marking its first rate hike since 2023; policymakers cited persistent inflation, alongside solid economic activity and resilient domestic spending, while signaling another increase remains possible before year-end
    • The market's focus broadened beyond Fed policy as investors increasingly grappled with rising Treasury yields, growing fiscal deficits, and geopolitical uncertainty amid tighter financial conditions
  • Economic data generally surprised to the upside; August payrolls increased 162k versus expectations of 55k, September's PMI Composite Index rose to 58.4, and the unemployment rate remained at 4.1%
  • Inflation remained elevated as August CPI increased 0.4%, above consensus, and Core CPI rose 0.3%; headline and core inflation ended at 3.4% and 2.4% year-over-year, respectively
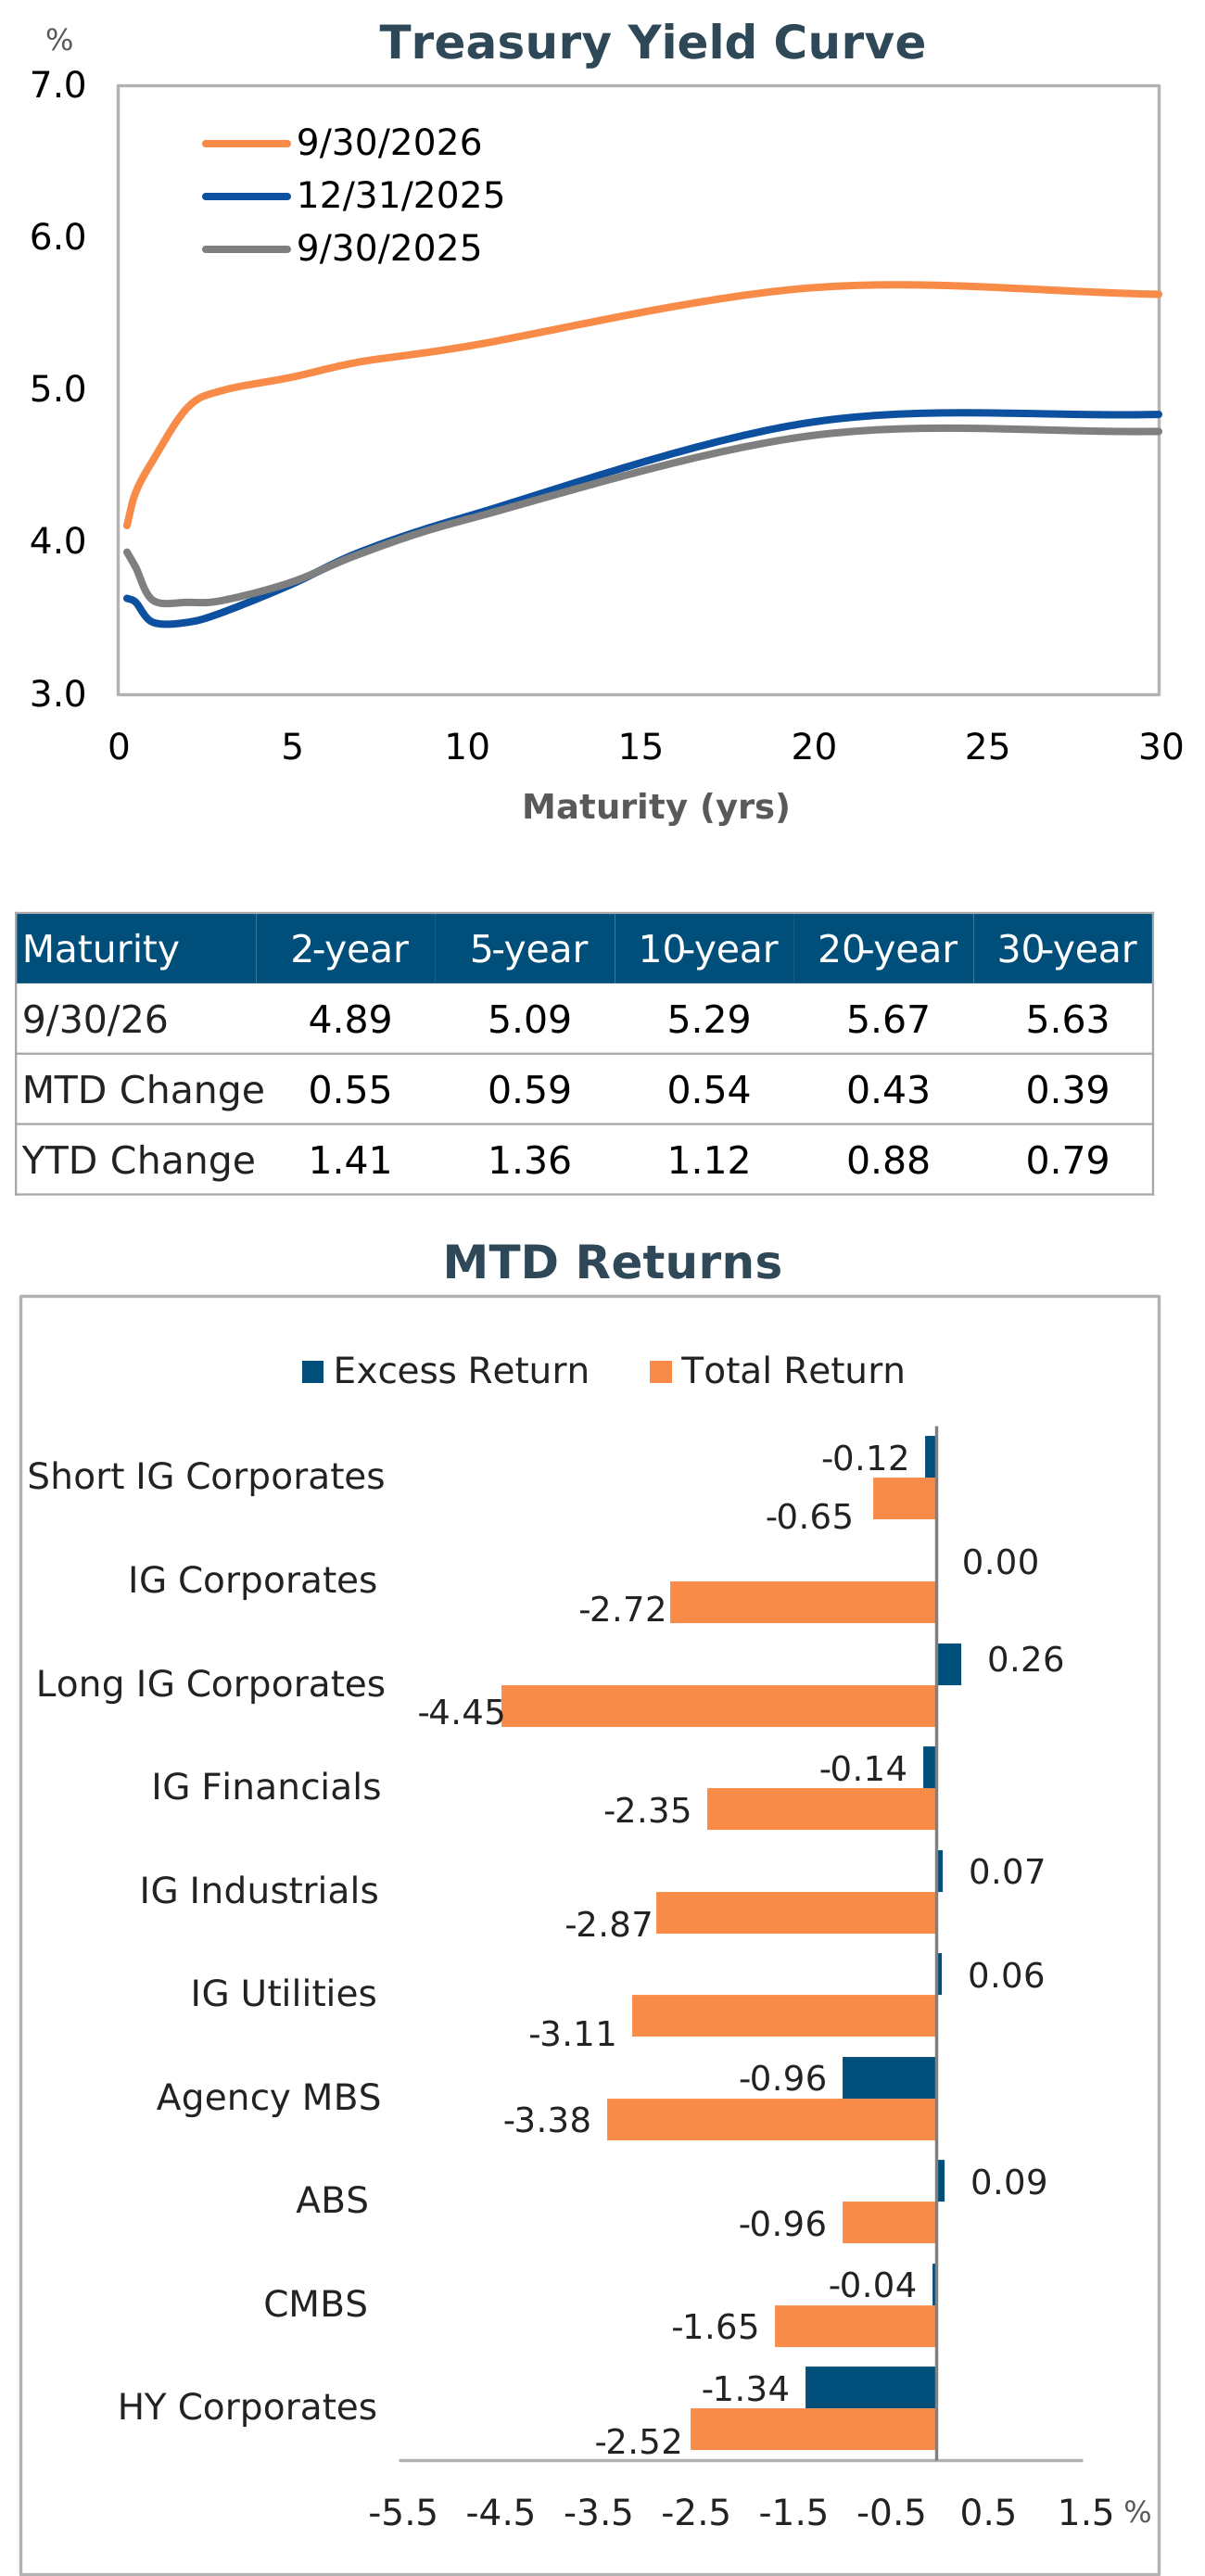
  • Treasury yields moved sharply higher during September as investors reassessed the outlook for inflation, monetary policy, and Treasury financing needs; the 5-year Treasury yield rose 59bps to 5.09%, one of the largest moves across the curve, while the 30-year Treasury yield reached 5.63%, its highest level in more than two decades,
    • A weak $70 billion 5-year Treasury auction reinforced concerns surrounding demand for government debt; investors increasingly questioned what yield level is required to absorb growing Treasury issuance as persistent fiscal deficits drive financing needs higher
  • Credit market performance diverged as lower-quality issuers proved more sensitive to rising market volatility; investment-grade (IG) spreads widened from 78bps to 80bps, and high-yield (HY) spreads increased from 261bps to 311bps, while all-in yields rose from 5.49% to 6.04% and 7.27% to 8.35%, respectively
    • HY posted its worst monthly loss since September 2022, and yields rose to a 17-month high
  • IG corporate supply totaled $195 billion, below expectations of $215 billion; year-to-date supply is up 31% to $1.7 trillion.
    • HY issuance measured roughly $51 billion, the highest monthly total in 2026, despite higher funding costs
  • Agency mortgage-backed securities underperformed most spread sectors; MBS spreads widened to approximately 36bps as elevated rate volatility was a headwind
  • Municipal bonds generally lagged Treasuries during the month; the 2-year muni/Treasury ratio rose from approximately 60% to 66%, while the 30-year ratio increased to roughly 92%


MARKET STATISTICS


As of 9/30/26. Sources: Bloomberg

Excess returns are the curve-adjusted excess return of a given index relative to a term structure-matched position in Treasuries. This is not a recommendation to purchase or sell the securities mentioned above.

The views contained in this report are those of Income Research + Management (“IR+M”) and are based on information obtained by IR+M from sources that are believed to be reliable but IR+M makes no guarantee as to the accuracy or completeness of the underlying third-party data used to form IR+M’s views and opinions. This report is for informational purposes only and is not intended to provide specific advice, recommendations, or projected returns for any particular IR+M product. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission from Income Research + Management. “Bloomberg®” and Bloomberg Indices are service marks of Bloomberg Finance L.P. and its affiliates, including Bloomberg Index Services Limited (“BISL”), the administrator of the index (collectively, “Bloomberg”) and have been licensed for use for certain purposes by IR+M. Bloomberg is not affiliated with IR+M, and Bloomberg does not approve, endorse, review, or recommend the products described herein. Bloomberg does not guarantee the timeliness, accurateness, or completeness of any data or information relating to any IR+M product.

Share this post

Related posts

View All
6 min read

Bond Appétit - The Active Manager's Discerning Palate

4 min read

The Next Hundred Days and Beyond

3 min read

Cashing In On Your Second Chance

As of 6/30/26 unless otherwise stated. Personnel Data as of 8/24/26.
@ 2026 Income Research + Management. All Rights Reserved.
chevron-down